⏱ 19 min read
Published September 15, 2026
How dual licensed real estate agents stay compliant
As a dual licensed real estate agent, you face a unique headache: one mixed social media post can trigger a state board investigation. You want to guide clients from house hunting to financing, but constantly checking Facebook posts for RESPA violations is exhausting. The fear of a CFPB audit forces many to abandon marketing entirely. Fortunately, you can safely run campaigns by correctly structuring your marketing content and automated follow-up systems.
- Every dual licensed real estate agent must strictly separate mortgage marketing from real estate marketing to avoid RESPA Section 8 violations regarding undisclosed compensation.
- The Consumer Financial Protection Bureau (CFPB) issued $1.75 million in RESPA penalties in a single recent enforcement action for illegal real estate kickbacks.
- Co-branded marketing materials must split costs proportionally between the loan officer entity and the real estate entity based on the exact ad space used.
- Compliant social media scheduling requires a 60/30/10 content mix that keeps loan education and listing promotion in separate posts.
Why does holding both a real estate and loan officer license trigger compliance flags so quickly?
Regulators scrutinize a dual licensed real estate agent because they assume one role might be used to steer unearned business to the other. RESPA Section 8 prohibits anyone from giving or accepting a thing of value for real estate settlement service referrals.
When someone acts as both the agent and the lender, the lines blur. A state board looks at a combined social media post and sees a potential undisclosed kickback. The Consumer Financial Protection Bureau (CFPB) enforces these rules strictly because they view mixed services as a setup ripe for steering. The National Association of Realtors reports that 18% of real estate members hold an additional license, and state regulators target these individuals during routine checks.
Disclosing your dual role early is mandatory. Hiding the disclosure in a contract addendum at the closing table violates compliance rules. Your marketing must clearly show two distinct businesses operating independently. If a buyer clicks a Facebook ad for a listing, that ad cannot imply they must use your mortgage services to win the bid. Messaging and backend systems must remain completely separate.
How do you split your weekly content between mortgage tips and listing marketing without confusing buyers?
A strict 60/30/10 schedule prevents you from mixing mortgage claims and listing details in the same post. This structured approach keeps your messaging clear and satisfies compliance officers reviewing your pages.
Buyers get confused when a new listing photo features a caption about current interest rates. They do not know if they are talking to a listing agent or a loan officer. Bucketing your content solves this problem.
Here is the breakdown for a compliant weekly schedule:
- 60% Real Estate Content: Neighborhood tours and active listings representing your brokerage role.
- 30% Mortgage Education: Explaining rate buydowns and pre-approval steps representing your lender role.
- 10% Personal Brand: Community involvement and local business highlights.
Putting a specific loan rate on a specific listing flyer crosses the compliance line. Instead, shoot a two-minute video explaining why home values in the Oak Park neighborhood jumped 12% last quarter and post that on Tuesday. On Thursday, publish a separate graphic explaining how a 2-1 buydown works. You can automate your real estate follow-up to send these different content types to the appropriate lists while keeping the topics isolated.
What specific disclosure text must appear on every co-branded social post and flyer?
Every co-branded post must include your NMLS ID, your real estate license number, the Equal Housing Opportunity logo, and a clear statement identifying both your brokerage and your mortgage company. State regulators check these exact items during an audit of any dual licensed real estate agent.
Typing “licensed agent and LO” in an Instagram bio is insufficient. Every piece of marketing that touches both businesses requires the full disclosure block.
| Requirement | Where it goes | Why you need it |
|---|---|---|
| NMLS ID | Every mortgage post | Federal requirement for all loan officers |
| Real estate license # | Every listing post | State board requirement for agents |
| Brokerage & Lender names | Clear and visible on the flyer | Proves you operate under licensed entities |
| Equal Housing logo | Any post discussing rates or housing | Fair Housing Act compliance |
| Dual role disclosure | Print materials and email footers | Informs consumers you hold both licenses |
This text must appear in the caption of single-image posts. Video content needs the disclosure visible on the screen or pinned as the first comment. Building templates in Canva with the disclosure block permanently locked at the bottom ensures you never publish a graphic missing the required numbers.
How can your admin or VA run co-branded marketing without breaking license laws?
An admin runs compliant marketing by using a folder of pre-approved templates that restrict them from writing new loan claims or modifying disclosures. Unlicensed assistants cannot legally discuss rates or loan terms.
Telling an assistant to quickly make a post about current rates invites massive risk. An untrained team member might accidentally post unapproved loan terms or alter required disclosures to improve the design, putting your licenses in jeopardy.
“Your assistant is there to schedule and publish, not to interpret state compliance laws,” says Rohan Attravanam, founder of nurtureBEAST.
Controlling the visual assets fixes this vulnerability. Build a Google Drive folder with 20 approved mortgage graphics and 20 approved real estate graphics containing baked-in disclosures. Give your VA a spreadsheet of pre-written, compliant captions.
Actionable Caption Template for VAs:
"Check out this market update for [Neighborhood]. Reach out to discuss local trends! | [Your Name] | NMLS ID: [XXXXXX] | DRE#: [XXXXXX] | [Brokerage Name] | [Lender Name] | Equal Housing Opportunity."
Their only job is to match the graphic to the caption and schedule it. You review the social media automation queue once a week. They never write original copy about loan products, which protects your business while still providing the full benefit of an assistant.
Which automated follow-up sequences keep loan leads and real estate buyers in separate tracks?
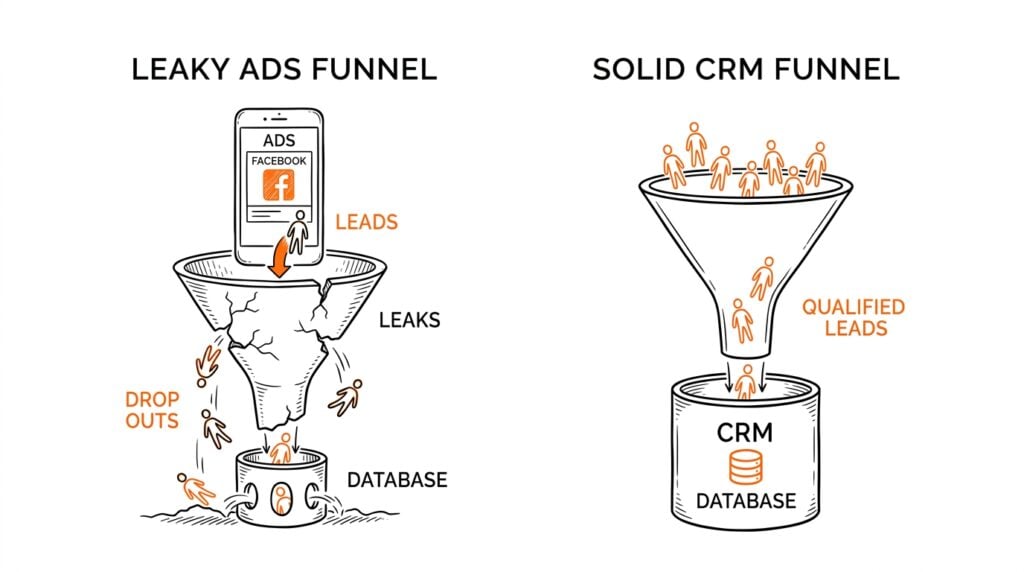
Building two distinct CRM pipelines that trigger different communication sequences based on the opt-in source keeps your leads compliant. A pre-approval inquiry never receives an open house follow-up text.
Mixing databases creates severe compliance headaches for a dual licensed real estate agent. If a prospect downloads a guide on FHA loans, automatically subscribing them to real estate listing alerts without permission breaks the rules. Clear real estate database management boundaries prevent this overlap.
You build this in GoHighLevel by tagging leads at the source. Mortgage leads receive a 14-day loan education sequence that texts them about pulling credit and gathering W-2s. Real estate buyers enter a neighborhood update sequence that texts them about weekend open houses and contract deadlines.
If a real estate buyer asks about financing, manually move them to the mortgage pipeline and send the required dual-role disclosure form. A GoHighLevel buyer’s agent workflow automates the real estate side, while the mortgage side runs on a completely separate track. The CRM does the heavy lifting to ensure the messaging stays compliant.
How do you feature partner lenders or co-marketing without getting hit with a RESPA violation?
Splitting the exact cost of the advertisement proportionally between the real estate agent and the partner lender prevents RESPA violations in co-marketing. Documenting every payment with invoices showing the percentage of space used is strictly mandatory.
A lender cannot pay for an entire Zillow ad spend just because they receive the leads. Splitting a billboard evenly is illegal if the lender’s logo only occupies a small fraction of the space. The CFPB views unequal payments as illegal kickbacks for referrals.
When running a Facebook ad campaign that features both real estate services and a partner loan officer, measure the pixels. If the ad gives equal visual weight to both parties, both pay exactly 50% of the ad cost directly to Facebook. Neither party pays the other; both pay the vendor.
Keeping a paper trail is essential. You must print the ad and highlight the visual space each party occupies. Finally, attach the vendor invoice showing two separate credit card charges to prove compliant billing. Store this in a compliance folder for five years so that when the state board audits your text message marketing, you hand them a clean, documented file.
What daily system handles dual-license nurture so you spend less than 30 minutes on marketing?
A daily system that pre-loads compliant newsletters and SMS campaigns for both the loan roster and buyer pipeline simplifies marketing. Reviewing the scheduled messages takes only a few minutes, leaving the rest of the day for calling warm leads.
Drafting compliant marketing each morning requires constant rule-checking. An automated system runs the follow-up while keeping licenses safe.
nurtureBEAST separates the database into clear segments. The software sends a compliant mortgage update to past loan clients on Tuesday and delivers a local market report to the real estate sphere on Thursday. Disclosures are hard-coded into the email footers. Any dual licensed real estate agent can just log in, check replies from people asking to buy or refinance, and make calls. Guessing if real estate email marketing breaks RESPA rules becomes a thing of the past. Locked templates and scheduled delivery mean you only have to handle the conversations.
Frequently asked questions
Can I offer a discount on my real estate commission if the buyer uses my mortgage services?
No, tying a real estate commission discount directly to the use of your specific mortgage services is generally viewed as a RESPA Section 8 violation. It acts as an illegal inducement for settlement services. You must keep pricing and incentives completely separate between the two businesses.
Do I need to disclose my dual license if I am only representing the client on the real estate side?
Yes, a dual licensed real estate agent must disclose their licensed status in both fields even if they are only acting in one capacity for a specific transaction. Transparency prevents the client from feeling misled if they discover your other business later. This proactive communication builds trust and satisfies most state compliance requirements.
Can my unlicensed assistant answer questions about current interest rates if a lead calls?
Absolutely not. An unlicensed assistant can only gather basic contact information and schedule an appointment for you to speak with the lead. Discussing rates or loan products requires an active mortgage license.
Related reading
- GoHighLevel Buyer’s Agent: 6-Stage Pipeline Setup Guide – Learn how to build a compliant CRM track specifically for your real estate buyers.
- Automate Real Estate Follow-Up: 3 Tracks to Build First – See the exact sequences needed to keep your messaging consistent without manual work.
- Real Estate Database Management: 4 Must-Have Pieces – Discover how to segment your loan clients from your buyer leads safely.
The Bottom Line
Operating as a dual licensed real estate agent provides a massive advantage in serving clients. Controlling the entire transaction allows for a smoother consumer experience. However, the compliance trap remains a significant threat. Regulators actively look for professionals who mix their marketing and fail to properly disclose their roles.
Implementing strict boundaries protects the business. Using approved templates for disclosures and maintaining distinct CRM pipelines ensures mortgage leads and real estate buyers receive entirely different automated follow-ups. Agents who implement these separated, compliant systems ensure their messaging is finally clear and consistent without the constant fear of an audit.
If you want to see how nurtureBEAST handles compliance and separate pipelines – take the quiz to find out what’s killing your real estate business or visit nurturebeast.com.